The Whole Job, Done For You.
Six stages, from mapping your capital to planning the next acquisition. We run all six. You approve two decisions.
- Since 1988
- 40+ years, multiple market cycles
- 6 years as CMHC’s Power of Sale listing team
- Southern Ontario
Six Stages, Start To Finish.
Each stage is work somebody has to do. The only question is whether it lands on your evenings or on our desk.
Portfolio Plan
Before any property is discussed, we establish how much capital is genuinely in play, what borrowing capacity sits behind it, what the money needs to do, and over what horizon. Risk tolerance is settled here, in plain terms, not assumed later.
Output: a written plan you can hold us to.
Curate Deal Flow
MLS and off-market listings are screened continuously through more than fifty filters, then narrowed against your plan specifically. You see the few that survive, not everything that exists.
Output: a shortlist, with the reasoning attached.
Review & Underwrite
Proforma, comparable sales, net operating income and debt service coverage, worked through before an offer exists. If the numbers only work on optimistic assumptions, we say so and move on.
Output: underwriting you review before we act.
Coordinate Execution
Offer strategy, financing, inspections, legal and closing, coordinated across a network of lenders, lawyers and inspectors who have done this with us before. You sign; you do not chase.
Output: a closed transaction, with one point of contact.
Stabilize The Asset
Renovations scoped, quoted and run. Tenants sourced and screened. Management put in place properly rather than improvised. This is the stage most first-time investors underestimate, and it is the one that decides whether the asset performs.
Output: an occupied, income-producing property.
Scale Planning
A refinance roadmap, so equity built in the first property can be put to work in the next one when conditions allow, and a clear view of when it should not be.
Output: a sequence, not a one-off purchase.
Buy Where The Path Of Development Is Already Going.
The most reliable signal about a neighbourhood’s next decade is what has already been committed to it.
Major builders assemble land years before they break ground. Transit and infrastructure are planned, funded and announced long before they open. Those decisions are public, and they are slow. We concentrate on the corridors where that commitment has already been made, rather than trying to guess which area becomes fashionable next.
It is a deliberately unexciting approach. It is also the reason the same markets come up again and again in our shortlists.
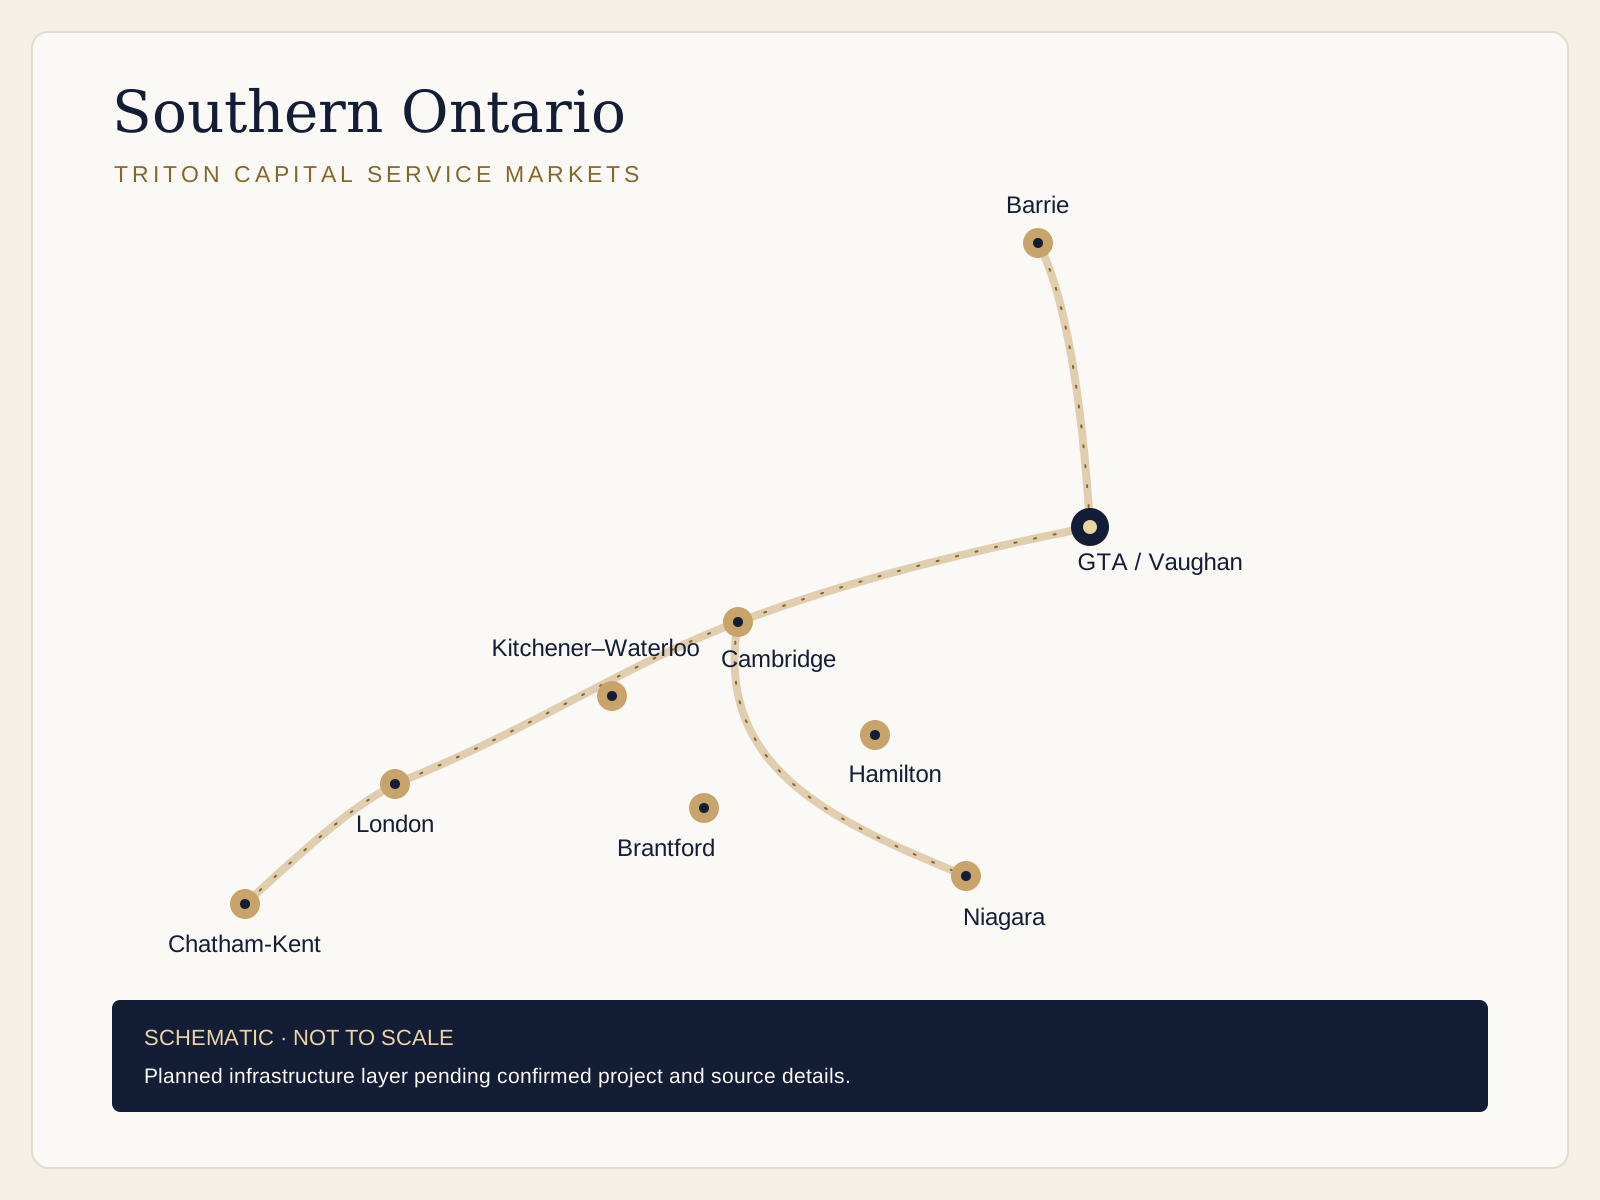 Schematic, not to scale
Four Lenses On Every Property.
A property has to survive all four. Most do not, and that is the point.
Location intelligence
Growth corridors, planned transit and infrastructure, and where major builders have already committed land. Location is the one variable that cannot be renovated later.
Property fit
Condition, unit mix, and how complicated the renovation actually becomes once somebody opens a wall. A cosmetic budget applied to a structural problem is how returns disappear.
Financial viability
Income durability, debt service coverage, and whether the vacancy buffer survives a bad quarter rather than an average one.
Exit options
Hold, refinance or sell, assessed before purchase. A property with only one way out is a property with no plan.
How the screening works
- 01MLS and off-market listings are pulled in continuously.
- 02Automated filters remove what does not fit your plan.
- 03The survivors are checked against four lenses: location, property, financials and exit.
- 04What is left is underwritten by hand before you see it.
Screening at that volume is not about finding more properties. It is about being able to say, with evidence, why the one you bought was better than the several hundred you did not.
Three Risk Profiles.
The plan is built to one of these deliberately, agreed at stage one, and not quietly drifted away from later.
Conservative
Stability first
Lower leverage, established neighbourhoods and stabilized properties. The priority is steady income and protecting capital.
Moderate
Balanced
A mix of stabilized income and value-add work. Some renovation risk in exchange for building equity faster.
Growth-oriented
Longer horizon
More value-add and repositioning, held over a longer horizon. More upside potential, with more variability along the way.
Each profile needs a written description from Triton. What “conservative” means in practice is a disclosure question, not a copywriting one, so nothing has been drafted here.
Five Sources, Not One.
Income property does not earn in a single way, which is why comparing it to a single rate of return misses most of the picture.
Cash flow
Rent received above the cost of holding the property.
Tenant-funded mortgage paydown
The loan balance falls each month, paid from rent rather than salary.
Appreciation
Change in the property’s value over the holding period.
Refinance proceeds
Capital released by refinancing against built equity.
Depreciation
Treatment of the asset for tax purposes.
An Illustrative 12-Year Portfolio.
One example of how the model can compound over time.
Fix-and-flip
$564K total profit: 111% gain
Strategies of 2 to 5 years.
Refinanced hold
Free $10M asset + $20K/mo cash flow
Buy, hold and refinance over 12+ years. Average hold 8.6 years.
Illustrative example only. Individual results vary based on market conditions, timing, capital, and strategy.
Who This Is Not For.
Said plainly, because finding out three meetings in wastes your time more than ours.
It fits if you are
- ✓A professional with strong income or borrowing capacity
- ✓A business owner looking to diversify outside the business
- ✓A pre-retiree building income streams for later
- ✓A disciplined, long-horizon wealth builder
- ✓A homeowner with equity you would rather put to work
It does not fit if you are
- ×Looking for short-term speculation
- ×Without liquidity reserves behind the purchase
- ×Uninterested in working inside a structured framework
The Things People Ask Before The Call.
Answered here, so the call can be about your situation instead.
How much capital do I need to start?
It depends on the plan: the property type, the market and how it is financed. We work out a realistic starting figure with you on the discovery call, based on your capital and borrowing capacity.
How much of my time does this actually take?
Very little. You make two decisions: approving the plan and approving each property. Sourcing, underwriting, renovations, tenants and management are handled by Triton.
Who holds title to the property?
You do. You buy the property and hold title to it. Triton finds it, improves it and manages it on your behalf.
What happens if a tenant stops paying?
Tenants are screened before they are placed, and arrears are followed up promptly by management. If it comes to that, the matter goes through Ontario’s Landlord and Tenant Board process. Every plan should also carry a reserve for vacancy and arrears.
How do I exit if my circumstances change?
You own the property, so you can hold, refinance or sell. Exit options are assessed before purchase, and if you decide to sell, Triton can handle the sale as your brokerage.
What does Triton charge, and how?
Fees depend on which services your plan uses. We go through them in full on the discovery call, before you commit to anything.
See The Model Explained In Full.
The training walks through all six stages with examples. Watch it, then book a call if it fits.
Or call 647-952-2440